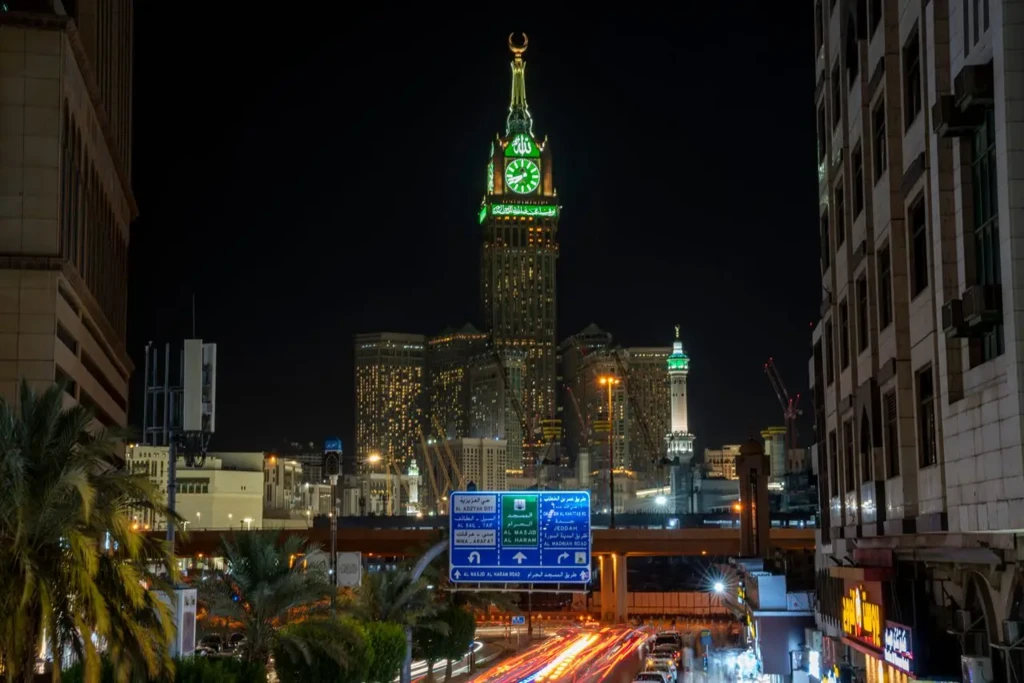
Site selection in Saudi Arabia affects far more than rent. It determines which landlord and regulator you deal with, how close you are to ports and rail, your access to feedstock and heavy utilities, and whether your output is treated as made in the Kingdom. One guide notes that location also influences the tax you pay and how much of the project the state will finance, so the decision is strategic, not administrative. The industrial landscape is usually explained through four “rulebooks”: MODON industrial cities, Royal Commission cities, Special Economic Zones (SEZs), and specialised hubs that can include logistics-oriented arrangements. A separate industry note cautions boards not to choose a site based only on a headline incentive or a promotional lease rate, because rules, permitted activities, customs arrangements, and investor services differ materially.
For many manufacturers, MODON is the default starting point. MODON is described as the “workhorse” landlord for most factories, with cities ranging from built-out sites inside Riyadh, Jeddah, and Dammam to newer tracts such as Sudair, which sits on the North–South railway and the Riyadh–Qassim highway. MODON offers ready-built factory units that can let a manufacturer start production in weeks instead of waiting for construction. However, mature cities in the three major metros are said to have little vacant land, so large plots may be more realistic in newer developments such as Riyadh 3rd, Dammam 3rd, Jeddah 3rd, and Sudair. MODON’s footprint is presented with multiple figures across sources: one reports 36 industrial cities, another 37, and one states the national factory count reached 13,660 in April 2026, with most of that base on MODON land; another estimates MODON’s cities host roughly 9,557 factories and logistics tenants.
When an Industrial City Beats an SEZ or Logistics Zone
Royal Commission cities are positioned for heavy industry at scale and integrated value chains. Jubail is described as about 1,016 km² and Yanbu as about 606 km², both built from the 1970s with their own ports, utilities, housing, and municipal services. Ras Al-Khair added minerals and shipbuilding, while Jazan City for Primary and Downstream Industries added a southern pole around an Aramco refinery. If your process needs gas, bulk berths, feedstock, or heavy utilities, one source says this is the system to evaluate first. By contrast, logistics-focused zones are framed around distribution and customs handling. A Vision 2030 investment guide describes the Integrated Logistics Zone (ILBZ) at Riyadh’s international airport as targeting logistics, e-commerce fulfilment, light manufacturing, and pharmaceutical distribution, including bonded logistics facilities with customs advantages.
SEZs sit between these models, with sector-focused frameworks and a distinct regulatory stack. Four zones were launched in April 2023, and their implementing regulations took effect on 16 April 2026. Companies must be established inside the zone as Saudi limited liability companies, and economic-substance rules apply from August 2026. For export-oriented manufacturing and distribution, sources repeatedly point to King Abdullah Economic City and Riyadh’s airport logistics zone. KAEC is described as hosting an automotive cluster where Lucid is assembling and Ceer and Hyundai are building plants beside King Abdullah Port. Another source places the KAEC SEZ roughly 100 kilometres north of Jeddah, anchored on King Abdullah Port, described as a top-100 global container port, and lists targeted sectors including automotive assembly and components, consumer goods, ICT, MedTech, and logistics.
A practical way to decide is to define the role Saudi Arabia will play in your group’s operating model before comparing plots. One industrial free-zone advisory notes the fastest movers design an industrial platform to serve the Kingdom, the wider GCC, and selected markets across Africa and Asia, rather than treating Saudi Arabia as a stand-alone export destination. That same source suggests leadership clarify whether the site will import components for final assembly, produce for Saudi demand only, hold inventory under a customs-efficient structure, or combine manufacturing with regional after-sales support. From there, align the project with the closest-fit zone: MODON for fast-start light and medium footprints and ready-built units; Royal Commission cities for feedstock- and utility-intensive complexes; an SEZ like KAEC for port-adjacent export logic and sector clustering; or a logistics zone like Riyadh’s ILBZ for bonded distribution, e-commerce fulfilment, and light assembly. Used carefully, manufacturing site selection Saudi Arabia becomes a structured comparison, not a guess.
How should manufacturers approach plant site selection in Saudi Arabia?
When does MODON make the most sense for a new factory?
Which Saudi locations are designed for heavy industry and integrated utilities?
What changed in Saudi Special Economic Zones in 2026?
Which zones are relevant for logistics, e-commerce fulfilment, or light assembly?
Talk to us for your needs in:
-
Economic & Social Impact Assessment
-
Environmental Impact Assessment & ESG
-
Market Entry Strategy
-
Business Model Transformation
-
Project Management Office (PMO)
-
Site Selection Advisory
-
Risk Assessment
-
Operational Excellence
-
Supply Chain Analysis
-
Feasibility Study
-
Growth Strategy
-
Mergers & Acquisitions (M&A)